Follow Us :
RDT Care Services Named #1 Home Care Provider in Silver Spring, MD — June 2026 BusinessRate Award
Follow Us :
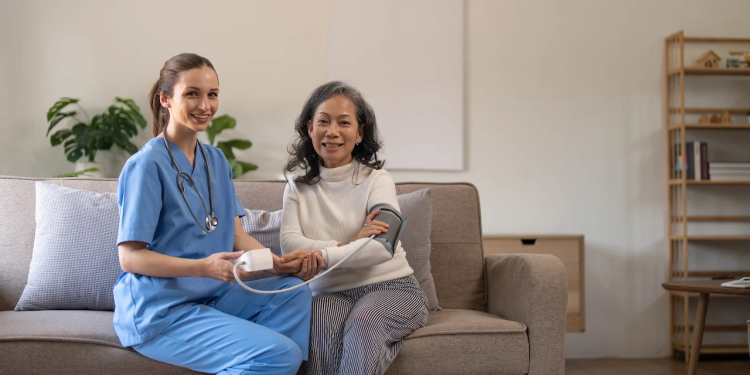
The first question most families ask about home care isn’t “who will take care of Mom?” It’s “how are we going to afford this?”
It’s a fair question. Home care is an ongoing expense, and most families haven’t planned for it. The good news is that very few families pay for everything out of pocket. Between government programs, veterans’ benefits, insurance, and smart scheduling, there are more ways to pay for home care than most people realize.
Here’s a plain-English breakdown of the main options available to families in Maryland, Washington DC, and Virginia.
Before looking at how to pay, it helps to understand what you’re paying for. Home care is typically billed by the hour, and the total depends on how many hours of support your loved one needs each week.
A senior who needs help a few mornings a week pays far less than someone who needs around-the-clock support. That’s one of the biggest advantages of home care over assisted living: you only pay for the care you actually use. Many families start with 10 to 20 hours a week and adjust as needs change.
Medicaid is the largest payer of long-term care in the country, and it doesn’t only cover nursing homes. Maryland offers programs that help eligible seniors receive care at home instead.
The two worth knowing about in Maryland are the Community Options Waiver and Community First Choice. Both can cover personal care services at home for seniors who qualify financially and medically. Virginia has the CCC Plus Waiver, and Washington DC has its own Elderly and Persons with Physical Disabilities (EPD) Waiver.
Eligibility rules involve income and asset limits, and there can be waiting lists, so it pays to apply early. Your local Area Agency on Aging can walk you through the application, and we’re happy to point families in the right direction as well.
If your loved one served in the military, or was married to someone who did, don’t skip this section.
The VA Aid and Attendance benefit is one of the most underused programs in senior care. It provides a monthly payment on top of a regular VA pension to veterans and surviving spouses who need help with daily activities like bathing, dressing, or eating. That money can be used to pay for in-home care.
Many families have never heard of Aid and Attendance, and many who have assume they won’t qualify. It costs nothing to find out. A Veterans Service Officer can review eligibility for free.
If your loved one purchased a long-term care insurance policy years ago, now is the time to dust it off. Most policies cover in-home care, though they vary widely in daily limits, waiting periods, and what triggers coverage.
Call the insurer and ask three questions: What does the policy pay per day for home care? Is there an elimination (waiting) period? And what documentation is needed to start a claim? A good home care agency can help provide care plans and records the insurer requires.
This is where families are most often surprised. Traditional Medicare covers short-term skilled care at home, such as nursing visits or physical therapy after a hospital stay, when ordered by a doctor. It does not cover ongoing, non-medical personal care like help with bathing, meals, or companionship.
Some Medicare Advantage plans now offer limited in-home support benefits, so it’s worth checking your specific plan. But for most families, Medicare is a supplement, not a solution, for long-term home care.
Many families do pay privately, at least in part. The key is building a care plan that matches real needs instead of overbuying hours.
A few ways families keep private-pay costs manageable:
Some families also use reverse mortgages, life insurance conversions, or shared family contributions. These are bigger financial decisions, so it’s wise to speak with a financial advisor before committing.
The worst time to sort out payment options is from a hospital waiting room. Applications for Medicaid waivers and VA benefits take time, and starting early gives your family real choices instead of rushed ones.
If you’re exploring home care in Maryland, Washington DC, or Virginia, RDT Care Services can help you understand what level of care your loved one needs and build a plan that fits your budget. Call us at 301 905 2172 or reach out through our contact page. The conversation is free, and it’s a lot easier than figuring all of this out alone.
Website: https://rdtcareservices.com
Facebook page: https://www.facebook.com/profile.php?id=61588373468664
Instragram: https://www.instagram.com/rdtcareservices
Tags :
Share This :